Every trade here is reproducible on your own machine
Most courses show you a screenshot. This one hands you the broker's own Strategy Tester reports — all 217 of them, openable one by one, losers included — and tells you exactly how to run them yourself.
What the reports prove
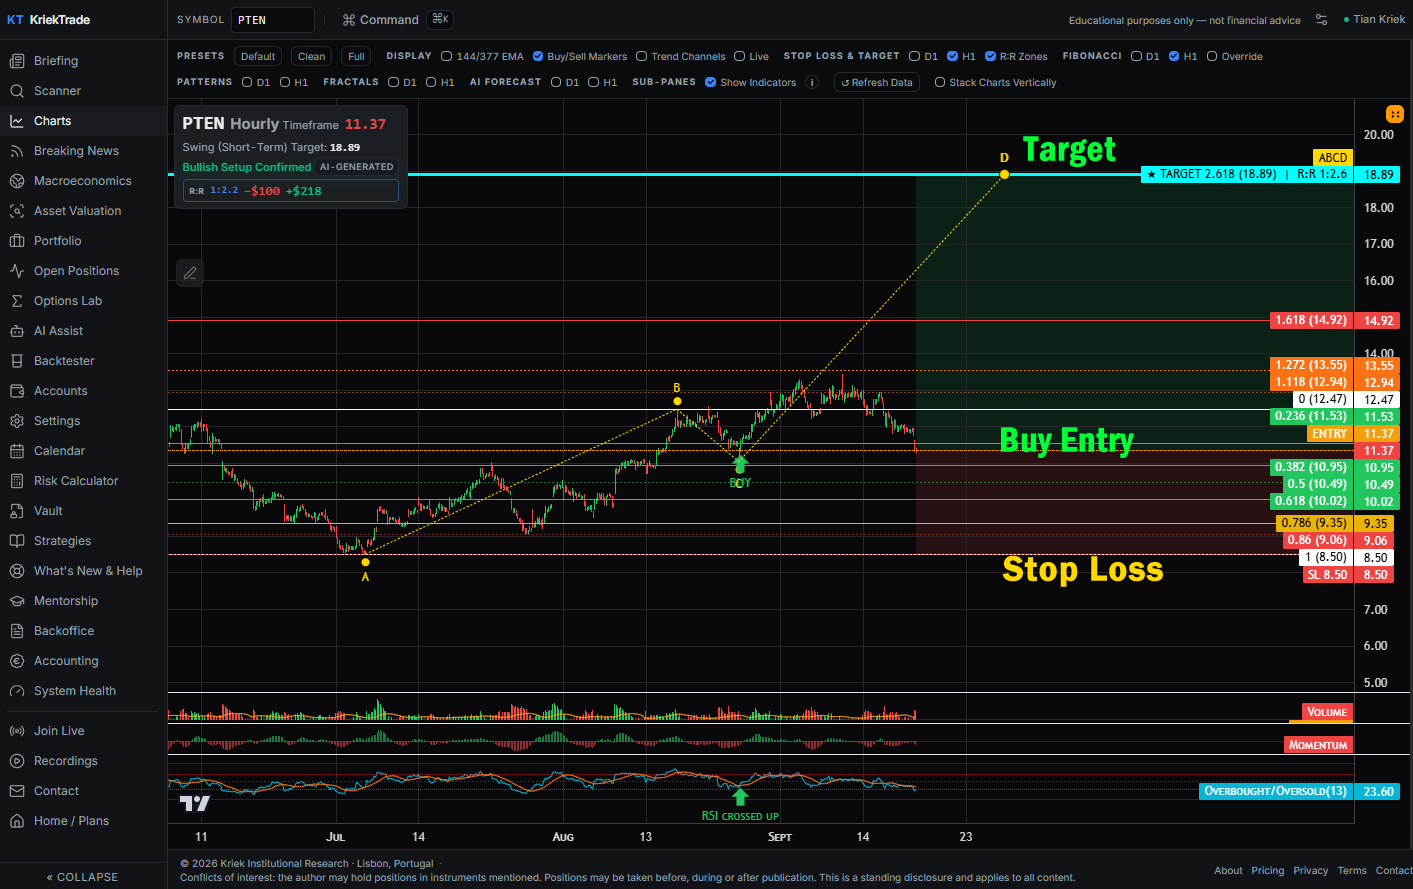
The signals are real and reproducible. An independent MetaTrader build, on two brokers' tick data, fires the same setups as the platform — same entries, same stops, same targets. That part is settled.
What they also prove
Where you hold a position decides what you keep. The same signals returned +68.2% before costs and +40.4% once real trading costs came out — because shares are held outright and currencies are carried on margin. Get that wrong and the whole edge goes to financing.
The same five years, before and after costs
Identical signals. The only thing that changes is what the trading costs. $10,000, 0.25% risk per
trade, 2021–2026.
| How the account is held | $10,000 becomes | Per year | Worst drawdown |
|---|
Before any costs
What the platform’s own backtester reports. No spread, no commission, no financing. | $16,818 | +11.2% | −12.7% |
Traded the way people actually trade
Currencies on MetaTrader at the broker’s real swap rates; shares, ETFs and crypto held outright in a funded account. 1,114 of the 1,544 signals — the rest skipped because the account could not fund them. | $14,040 | +7.2% | −8.7% |
The gap between those two rows is a lesson, not a disclaimer. This strategy holds a
position for 45 days on average, so what you are charged to carry it matters as much
as the entry. Held outright, a share costs nothing to carry. Financed overnight on a contract for
difference, the same 45 days can cost more than the trade makes — and the course shows you the
arithmetic on real reports rather than asserting it. Currencies work the other way and are the part
most traders get backwards: of the 28 pairs tested, 16 paid you to hold them and only
12 charged you, and on seven pairs the sign flips depending on which broker you use.
Carry is a rate you can be on the right side of, not a fee you simply pay.
Five-year test
176
instruments traded together on one account, 2021–2026, on five full years of the broker’s own hourly data. Forex, indices, metals, energy, crypto and US shares.
Return before costs, 0.25% risk
+68.2%
$10,000 to $16,818 over 4.9 years — 11.2% a year. Gross: no spread, commission or financing. After real costs it was +40.4% — see the table below.
Worst drawdown
−12.7%
The deepest fall the account lived through. The figure that decides whether you could have stayed with it.
Signals reproduced exactly
220 / 220
Every setup the platform fired, matched field for field by an independent MetaTrader build on two brokers' data. The signals verify; the costs are what differ.
What 1% risk would have made, before costs. The same 1,544 trades at 1% risk per trade turned $10,000 into
$74,257 — a 643% gain, 50.5% a year, on the same gross basis as the top row above. We do not teach that, and the reason is in the same
data: at 1% the account put a large multiple of its equity at risk simultaneously and fell
42% at its worst. The course teaches 0.25% because it is the version a
real account survives.
The same strategy, three risk settings
All four are before costs, so they can be compared with each other. Apply the venue table above to any of them.
| Test | Risk / trade | $10,000 becomes | Per year | Worst drawdown |
|---|
| Swing — what the course teaches | 0.25% | $16,818 | +11.2% | −12.7% |
| Swing at half risk | 0.5% | $27,935 | +23.3% | −23.9% |
| Swing at full risk | 1.0% | $74,257 | +50.5% | −42.3% |
1,544 swing trades, profit factor 1.30. Simulated results on historical hourly data,
2021–2026. The platform’s backtester excludes spread, commission and swap; the MetaTrader reports include all three —
which is the whole reason the venue table above exists. The New Zealand dollar pairs and the VIX are excluded because five years of testing said
they do not work. Every price series here is the broker’s own five-year hourly history, pulled from the
platform that produced the Strategy Tester reports below — not a third-party feed, and not stitched together from
different sources.
Independent verification
MetaTrader Strategy Tester reports — 180 on Ava Trade, 37 on RoboForex — 170 at 100% real-tick quality.
Open any of them, including the 127 that lost money.
Trades the macro filter refused
2,531
Across the 37-symbol RoboForex run, 68% of the 3,747 valid setups were declined because the macro regime was against them. Losses avoided, not opportunities missed.
Forward test
Live
Running on a RoboForex MT4 demo since 14 August 2026, forex only, using the same signals you will receive.